Owning Property Abroad Is Not the Problem — Failing to Disclose It Could Be
Imagine this.
You bought a property in Dubai a few years ago.
Or perhaps you invested in an overseas property while working outside India.
You paid for it using your savings.
You have not earned any rental income from it.
And you believe there is nothing to worry about.
But there is one question you may have overlooked.
Was the foreign property required to be disclosed in your Indian income tax return?
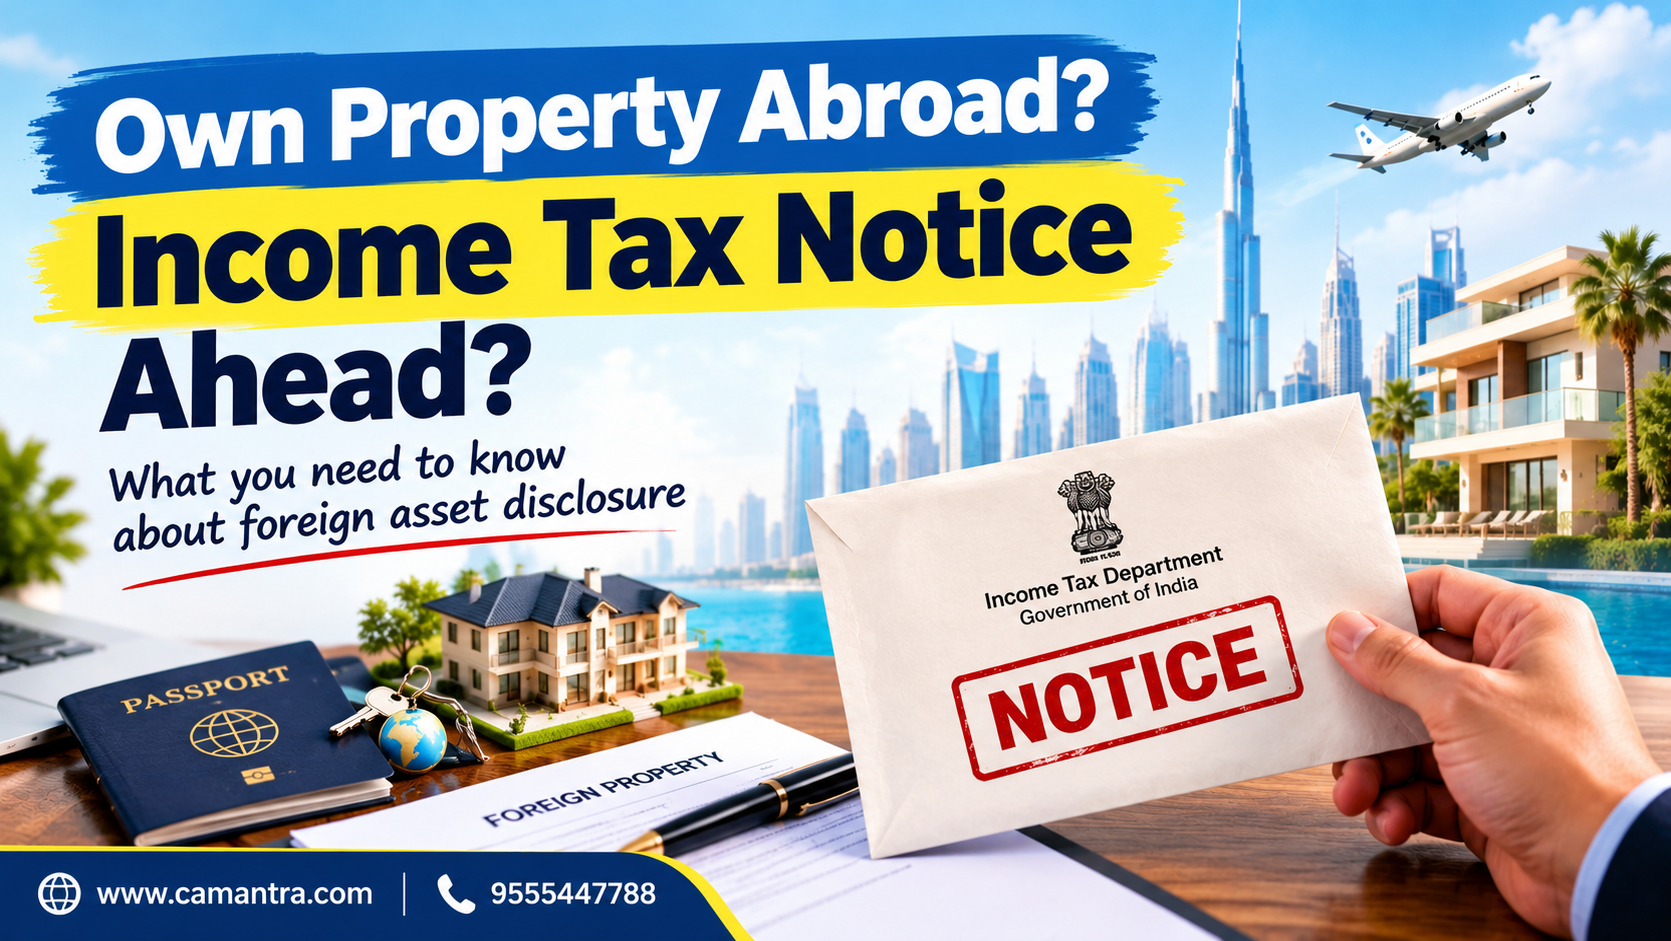
The Income Tax Department is increasingly using information received from international sources to identify potential gaps in foreign asset reporting, and is expected to issue notices to certain Indian residents over undisclosed foreign properties.
For taxpayers who have not reviewed their foreign asset disclosures, this is an important reminder.
Because sometimes, the problem is not how you acquired an asset.
It is whether you reported it correctly.
Why Is the Income Tax Department Looking at Foreign Properties?
A common assumption among taxpayers is:
“My property is outside India. Why would the Indian Income Tax Department know about it?”
That assumption can be risky.
International information-sharing arrangements allow tax authorities to exchange certain financial information. The Income Tax Department may also obtain information through specific requests, spontaneous exchanges and other investigation sources.
In simple terms, information about overseas financial interests can reach Indian tax authorities through multiple channels.
This does not mean every foreign property is automatically reported to India.
But it does mean taxpayers should not assume that overseas assets will remain invisible.
When information received by the department does not match the taxpayer’s income tax return, questions may arise.
And those questions may relate to ownership, the source of funds, foreign income and disclosure requirements.
Mistake #1: Assuming Foreign Property Does Not Need to Be Reported
This is one of the most important mistakes taxpayers should avoid.
Many people believe that if a property is located outside India, it does not need to be mentioned in their Indian income tax return.
But the reporting requirement generally depends on the taxpayer’s residential status and the applicable tax rules.
For example, a resident and ordinarily resident individual may be required to disclose specified foreign assets in Schedule FA of the relevant income tax return.
This may apply even when:
- The property does not generate rental income.
- The property was purchased several years ago.
- The property was acquired using savings earned abroad.
- The property is jointly owned with a spouse or another person.
The important distinction is this : Reporting a foreign asset and paying tax on income from that asset are two different things.
A property may not generate taxable income in a particular year, but that does not automatically remove the obligation to disclose it.
Mistake #2: Believing That Legitimate Money Means No Compliance Risk
Suppose you purchased an overseas apartment using salary earned while working abroad.
The salary was legitimate.
The purchase was genuine.
You have documents proving the source of funds.
Does that automatically mean there is no issue?
Not necessarily.
If you were required to disclose the property in Schedule FA but failed to do so, there may still be a reporting problem.
The source of investment and the disclosure of the asset are separate compliance questions.
This distinction is particularly important for people who:
- Returned to India after working overseas.
- Became Indian tax residents after several years abroad.
- Acquired foreign assets before moving back to India.
- Purchased overseas property using income already offered to tax.
The good news is that the explanation for the source of funds can be important when assessing the correct compliance route.
But it should not be assumed that a legitimate source automatically cures every disclosure omission.
Mistake #3: Forgetting Schedule FA While Filing Your ITR
Most taxpayers focus on familiar items while filing their returns.
Salary.
Interest income.
Capital gains.
Deductions.
But foreign assets may require separate reporting.
Schedule FA is the foreign assets schedule in applicable income tax return forms.
Depending on the circumstances, it can cover specified overseas holdings, including foreign immovable property, bank accounts, financial interests and other foreign assets.
Some taxpayers overlook this requirement because their accountant or employer has already reported the related income.
Others assume that reporting a foreign investment in one place automatically satisfies every disclosure requirement.
That may not be correct.
For example, an employee may have received shares under a foreign company’s Employee Stock Ownership Plan (ESOP) or Restricted Stock Unit (RSU) arrangement.
The related compensation may have been included in salary income.
However, the foreign asset may still require separate reporting under the applicable rules.
This is why checking the correct ITR form and its foreign asset disclosure requirements matters.
Mistake #4: Assuming No Rental Income Means No Tax Issue
Consider another example.
An Indian tax resident owns a residential property in Canada.
The property is kept for personal use.
No rent is received.
The owner assumes there is nothing to report because there is no income from the property.
But the absence of rental income does not automatically eliminate the foreign asset disclosure requirement.
If the property falls within the applicable reporting provisions, it may still need to be disclosed.
Similarly, if the property generates rental income or is sold at a profit, additional tax questions may arise depending on the taxpayer’s residential status, the nature of the income and the applicable provisions.
The lesson is simple. Do not judge your foreign asset reporting obligations only by whether the property earned money during the year.
What Happens If You Do Not Disclose Foreign Assets?
This is where things can become serious.
Failure to comply with applicable foreign asset disclosure or foreign income reporting requirements can expose a taxpayer to proceedings under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015, depending on the facts and the applicable statutory provisions.
Potential consequences may include:
- Questions about the source of investment.
- Requests for ownership and acquisition documents.
- Scrutiny of foreign income and previous income tax returns.
- Substantial tax and penalty exposure.
- Prosecution in cases where the relevant legal conditions are satisfied.
However, receiving a notice does not automatically mean that a taxpayer has committed tax evasion.
The department may seek clarification, and the taxpayer’s explanation, documentation, residential status and applicable legal provisions all matter.
The worst approach is to ignore the issue and hope it disappears.
FAST-DS 2026: An Opportunity to Correct Certain Past Omissions
There is another important development taxpayers should know about.
The government introduced the Foreign Assets of Small Taxpayers – Disclosure Scheme, 2026 (FAST-DS 2026).
The scheme provides an opportunity for eligible taxpayers to declare specified foreign assets or foreign income that were not previously disclosed, subject to the prescribed conditions.
It is particularly relevant for people whose foreign assets may have been omitted because of a reporting mistake, a change in residential status or a misunderstanding of their disclosure obligations.
But the scheme does not cover every situation.
Eligibility depends on the category of omission, the value of the assets or income, the source of funds and other conditions.
Who May Be Eligible?
The scheme broadly addresses two categories.
Category 1: Foreign assets or income that were not previously taxed
This category covers specified undisclosed foreign assets or foreign income, subject to an aggregate value limit of ₹1 crore.
The prescribed payment is generally 30% of the declared value or income, plus an additional amount equal to that tax.
This results in an effective payment of 60% of the declared amount, subject to the scheme’s conditions.
Category 2: Assets acquired from explained sources but not properly disclosed
This category covers certain foreign assets acquired from income earned while the taxpayer was a non-resident, or from income already offered to tax in India, where the required foreign asset disclosure was omitted.
The aggregate value of eligible assets must not exceed ₹5 crore.
The prescribed payment for this category is a fixed fee of ₹1 lakh, subject to the applicable conditions.
These categories are different. A taxpayer should not assume that the fixed-fee option is available simply because the source of funds can be explained.
What Is the Deadline?
The scheme commenced on 16 August 2026.
The last date for filing the declaration in Form 1 is 31 December 2026.
The prescribed valuation date is 31 March 2026.
Eligible taxpayers considering the scheme should review the applicable rules and documentation requirements promptly.
A valid declaration and compliance with the prescribed payment process may provide protection from specified tax, penalty and prosecution consequences under the Black Money Act for matters covered by the scheme.
However, the scheme has exclusions and conditions. It is not a blanket immunity for every foreign asset or every tax default.
What Should You Do If You Own Property Abroad?
If you own overseas property, a few practical checks can help you identify potential reporting gaps.
- Check Your Residential Status
Your tax residential status can determine whether foreign assets and income need to be reported in India.
Do not rely only on your citizenship or the country in which you currently live.
- Review Your Previous ITRs
Check whether your foreign property was required to be disclosed in Schedule FA for the relevant years.
Also review whether any foreign income needed to be reported separately.
- Collect Supporting Documents
Keep your property purchase agreement, ownership documents, bank statements, remittance records and evidence explaining the source of funds.
These documents can help establish how and when the property was acquired.
- Identify the Nature of the Omission
There is a difference between an asset acquired from legitimate, already-taxed funds that was not disclosed and an asset whose source of investment cannot be satisfactorily explained.
The appropriate tax treatment and available compliance options may differ.
- Evaluate FAST-DS 2026, If Applicable
If you identify an omission, assess whether you qualify for the scheme before deciding how to proceed.
Review the applicable asset valuation, payment requirements, eligibility criteria and exclusions with a tax professional.
- Do Not Ignore an Income Tax Notice
If you have already received a notice, read it carefully.
Understand what information has been requested, the relevant assessment year and the response deadline.
A timely, properly documented response is generally preferable to ignoring the communication or submitting an incomplete explanation.
A Simple Foreign Asset Compliance Check
Ask yourself:
✅ Do I own any property or financial assets outside India?
✅ Have I checked my residential status for the relevant years?
✅ Were my foreign assets disclosed in the applicable ITR forms?
✅ Have I reported foreign income wherever required?
✅ Can I explain the source of funds used to acquire my overseas assets?
✅ Have I reviewed whether any previous disclosure needs to be corrected?
If you answered “no” to any of these questions, it may be worth reviewing your position.
A small omission identified early can be easier to address than one discovered during a tax investigation.
The Bigger Lesson
Owning an overseas property is not, by itself, a tax offence.
Failing to understand the reporting requirements, however, can create avoidable complications.
In today’s increasingly connected financial environment, taxpayers should ensure that their income tax returns accurately reflect the information they are required to disclose.
The key is not to panic.
It is to review your facts, maintain proper documentation and take the correct compliance steps.
Final Thought
Your foreign property may have been purchased legally.
Your money may have come from legitimate sources.
You may not have earned a single rupee in rental income.
But one important question remains:
Have you disclosed the asset correctly under Indian tax law?
With the Income Tax Department increasing its focus on foreign asset reporting and the FAST-DS 2026 declaration window closing on 31 December 2026, this is a good time for eligible taxpayers to review their records.
Because when it comes to tax compliance, identifying a mistake is only the first step.
Taking the right action is what matters.